A cash-out refinance replaces your mortgage with a larger loan and pays the remaining proceeds to you after required payoffs and costs. I want you to compare the new payment and total borrowing cost before deciding. For a Texas homestead, state equity-loan rules also affect how much you can borrow and when you can close.
What Is a Cash-Out Refinance?
A cash‑out refinance replaces your existing mortgage with a new, larger loan and hands you the difference in cash. It works like swapping an old loan for a bigger one, then walking away with the extra cash at closing. The new loan pays off the old balance, covers closing fees, and any leftover amount lands in your bank account.
For a Texas homestead equity loan, the new debt plus other loans secured by the home cannot exceed 80% of its fair market value. This limits total secured borrowing, not the cash you receive. Other properties and programs have their own limits. See the Texas Department of Banking’s home-equity guidance.
Seasoning depends on the loan program and transaction. Fannie Mae generally requires six months on title and, when an existing first mortgage is paid off, a note at least 12 months old. Exceptions apply. These are Fannie Mae requirements, not a universal Texas ownership law.
Key Takeaway: Cash-out borrowing increases the debt secured by your home. Your payment depends on the new balance, interest rate and term; it does not always rise or fall in the same direction as the balance.
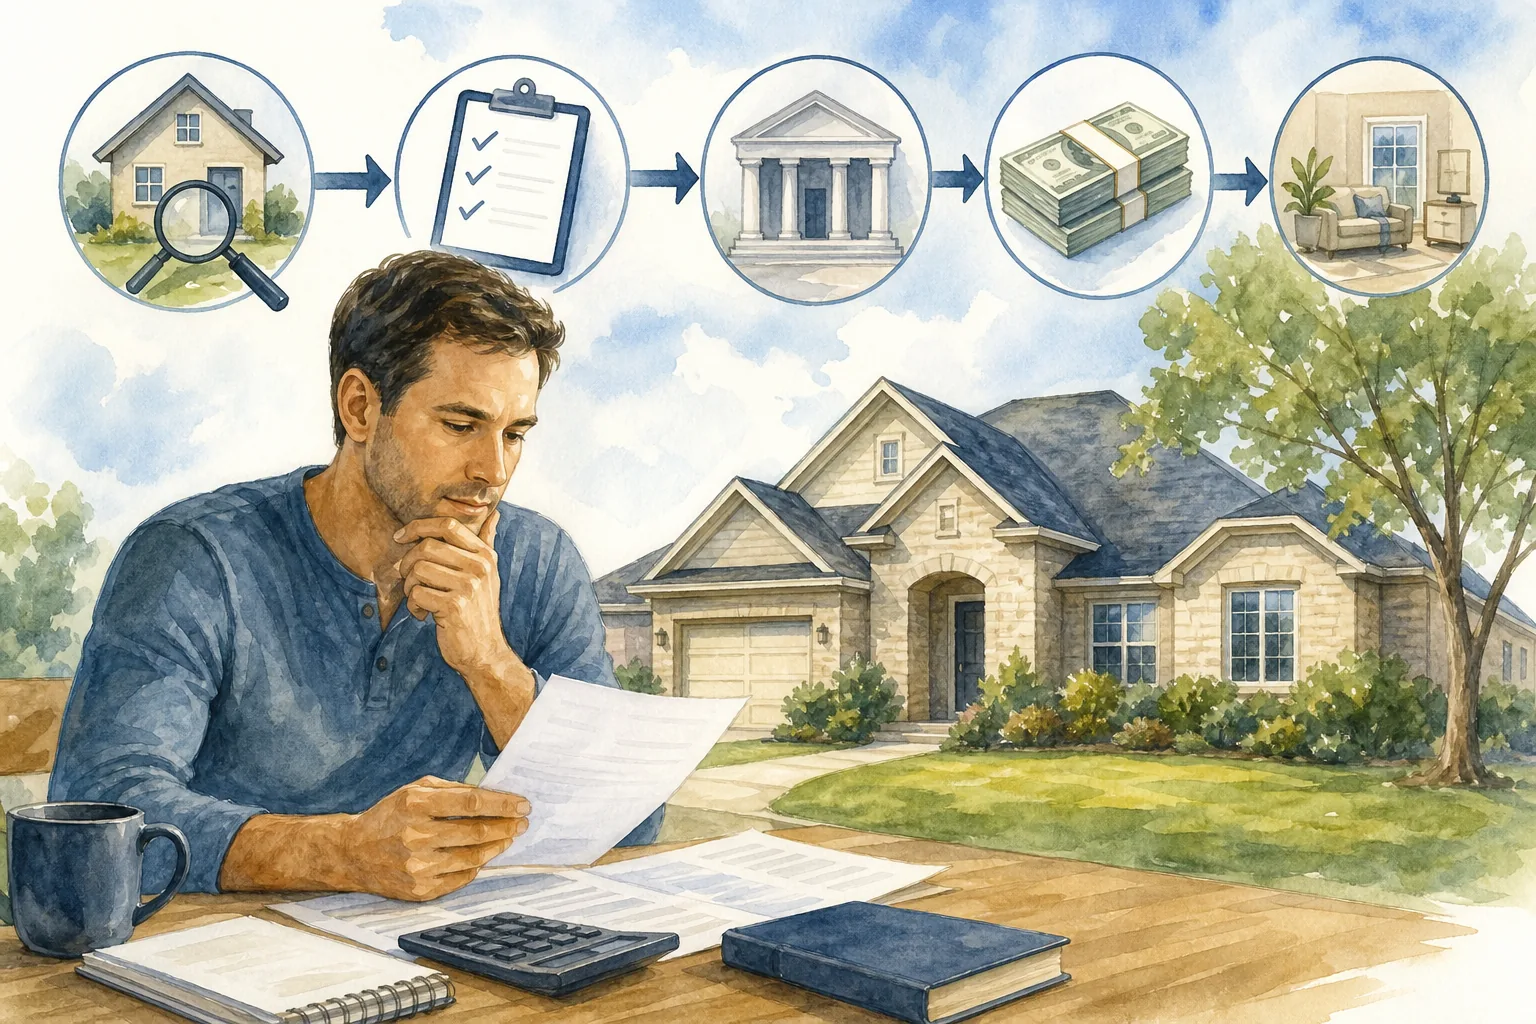
How the Cash-Out Refinance Process Works
First, the lender checks credit, income and other underwriting information. An appraisal estimates value; a separate title review identifies recorded liens and other title matters. Neither guarantees approval. Ask which checks remain before making commitments based on expected loan proceeds.
The lender applies the relevant combined loan-to-value limit and subtracts debts that must be paid off, fees and other required amounts. For a Texas homestead equity loan, use the 80% combined-debt ceiling when estimating the available amount. A preliminary calculation is not a loan offer.
The new loan then pays off the old mortgage. Any remaining funds, after closing fees, are disbursed to you. You’ll sign a new promissory note and a revised deed of trust, which resets your amortization schedule.
Texas homestead equity loans have separate timing and notice requirements. The state generally requires a year between home-equity loan closings, with specific exceptions, plus a prescribed pre-closing waiting period. Its mortgage regulator’s report, pages 28 to 29, explains these rules. Ask the lender which requirements apply to the existing and proposed liens.
Costs, Interest Rates, and Tax Considerations
Closing costs associated with a cash‑out refinance can total thousands of dollars, including appraisal, title, recording, and lender origination charges. Some lenders let you finance these fees, which reduces the cash you walk away with.
Compare current written Loan Estimates for the same loan amount and term. Review the rate, APR, points, closing costs and total payment. Refinancing replaces the rate on the whole existing mortgage balance. Keep a separate comparison that leaves your current first mortgage in place and adds the proposed second loan. Include both payments and their remaining terms. Ask the lender to explain any difference in the cash you receive, since equal monthly payments can accompany different balances and costs.
The cash-out portion may qualify for the home-mortgage interest deduction when it is used to buy, build or substantially improve the qualified home that secures the loan. You must also meet itemizing, debt-limit and other requirements. Ordinary maintenance alone generally does not qualify. Keep records and consult IRS Publication 936 and your tax professional.
There is a cap on deductible mortgage debt for loans taken out after 2017. If your pre‑refinance balance is already near that limit, the extra cash‑out amount may push you above the cap, affecting how much interest remains deductible.
For an explanation of points, see Mortgage Points Explained: Costs and Break-Even. Compare the up-front cost with the potential savings over the time you expect to keep the loan.
Benefits, Risks, and Common Misconceptions
Debt consolidation can replace several payments with one, but compare total costs over the full repayment term. Moving unsecured debt into a mortgage puts your home behind that debt. A lower rate or monthly payment does not necessarily mean you will pay less overall.
Cash-out funds can pay for home improvements. Compare written project quotes with your budget, and do not assume the work will add its cost to the sale price. You must repay the loan even if the project does not increase your home’s value.
The main risk is losing the home if you do not meet the secured loan’s repayment terms. Borrowing more also leaves less equity for a sale or future need. Declining values can make that problem worse. Review an affordable payment and a contingency plan before closing.
Extending the repayment term can increase total interest even when the monthly payment falls. Compare the same loan balance at the same rate over different terms, then review the actual rates and fees in your Loan Estimates. A smaller required payment leaves more room in a monthly budget, but it does not establish a cheaper loan.
Be wary of offers that claim you can skip payments or obtain unusually low interest rates. These promises may not be legitimate.
Cash-Out Refinance Alternatives for Texas Homeowners
A separate home equity loan can leave your existing first mortgage in place. It adds another debt secured by the home, so compare the combined payments and costs. In Texas, the existing liens and homestead rules affect whether this structure is available. Ask the lender to explain the complete arrangement.
A home equity line of credit (HELOC) works like a credit card tied to your home’s equity. You draw funds as needed, and the rate is often variable. It’s handy for staggered projects but can swing higher if market rates rise.
An unsecured personal loan does not use the home as the loan’s collateral. Compare its rate, fees and repayment term with the alternatives. Missing payments can still lead to credit damage, collection and legal consequences; unsecured does not mean risk-free.
Program eligibility does not override Texas homestead-lending restrictions. Ask a properly licensed lender to confirm which loan types can be offered for your property and existing lien structure, rather than assuming a national program applies.
Before you decide, run the numbers with a budget review. It helps you see how a higher loan balance will affect your monthly budget.
Another resource is an appraisal guide. During a refinance, the lender will order a home appraisal to assess the property’s value.
FAQ: Cash-Out Refinance Questions Answered
Can I do a cash‑out refinance only six months after buying my home?
Possibly, but the title-holding period is only one requirement. Fannie Mae generally also requires an existing first mortgage being paid off to be at least 12 months old. Exceptions and separate Texas homestead-equity rules may apply. Have the lender confirm the full set for your transaction.
How much cash can I actually receive?
For a Texas homestead equity loan, the new loan plus other secured debt cannot exceed 80% of the home’s fair market value. Subtract the debts paid off, closing costs and other required amounts to estimate the cash available. Underwriting can further limit the amount.
Will the cash I get be taxed as income?
Ordinary loan proceeds are generally not federal taxable income because you have an obligation to repay them. Cancellation of debt can have different tax consequences. The interest deduction is a separate question; review the use of the money and the conditions in IRS Publication 936 with your tax professional.
Do I have to keep the cash‑out refinance for a certain time before I can refinance again?
A Texas home-equity loan generally cannot be refinanced before its first anniversary. Certain no-cash-out conversions have their own conditions, and specific exceptions exist. Loan modification is different from replacing the note. Confirm the applicable rule with the lender; do not apply a blanket waiting period to every Texas mortgage.
What’s the biggest mistake borrowers make?
Many overlook the hidden cost of higher interest over a longer term. Even if the monthly payment feels lower, the total interest paid can exceed the savings from debt consolidation.
Conclusion
A cash-out refinance deserves a full cost and repayment comparison before you choose it. Ask a Texas-licensed lender for written terms and discuss tax questions with your tax professional. For questions about a home sale or purchase, contact Robbie English, REALTOR, Broker at Uncommon Realty. My real estate role is separate from underwriting or tax advice.