Thinking about buying a home in Taylor, TX? The numbers show a modest price rise even with plenty of listings. Here’s a clear, step-by-step guide to help you understand the market, costs, inspections, and closing process.
Too Long; Didn’t Read
- Taylor’s median list price is about $299K, with roughly 346 active listings and about 76 days on market.
- Location drives your commute, so compare drive times on the roads you would use every day.
- Add property taxes, insurance, and any HOA or MUD fees to your mortgage payment before you set a budget.
- Get a pre-approval and a full inspection before you commit.
- A Texas purchase usually closes through a title company in about 30 to 45 days.
What You’ll Find in the Taylor Housing Market
Taylor’s median list price sits around $299 K, and the average price per square foot is $187, according to Realtor.com. There are about 346 active listings, and homes spend roughly 76 days on the market. That mix of supply and a steady-rise price (8.7% year-over-year) gives buyers a slight edge but still requires a smart offer.
The inventory ranges from entry-level single-family homes to newer townhomes and larger acreages. A typical three-bedroom house is the most common type, but you’ll also see newer construction built after 2015 and older homes that need a little TLC.
Because the market updates daily, it helps to filter by price, beds, baths, and lot size. Homes for Sale in Hutto, TX: Prices, Growth, and What to Know illustrate how neighboring towns can affect inventory and price trends.
When you compare listings, look at the days on market and any price reductions. A home that’s lingered longer than the 76-day average may have hidden issues or simply be overpriced.
In short, you have choices, but you need data to decide which property fits your budget and timeline.
How Location Shapes a Taylor Home Search
Location in Taylor isn’t just a point on a map; it drives commute times, school options, and future growth. The city sits northeast of Austin, making it a convenient spot for workers commuting to nearby employment centers.
You’ll find newer subdivisions with modern finishes as well as older houses near downtown, some on larger lots. Visit several areas and compare them yourself before you narrow your search.
Proximity to major roadways such as US-79, SH-95, and SH-130 matters if you’re commuting to Austin or Round Rock. Drive the route at rush hour before you decide.
School options also play a role. Many buyers look at school ratings when narrowing down areas.
Another factor is future development. Check the city’s planning documents for new roads, parks, or commercial projects near a home you like, since they can change traffic and future demand.
For a broader view of how nearby markets compare, see Homes for Sale in Georgetown, TX: Prices, Neighborhoods, and What to Know. It shows how a short drive north or south can change price points and amenities.
When you pick a location, match it to your lifestyle, whether you need a quick commute, a quiet suburb, or easy access to shopping and dining.
Look Beyond the Asking Price: Taxes and Ownership Costs
Texas property taxes are a big piece of the monthly bill. In Taylor, property tax bills vary by property and the taxing entities that apply.
Property taxes help fund local services, including schools, police, fire, and road maintenance. Rates can vary across Taylor depending on applicable school district levies and municipal utility districts.
Don’t forget HOA or MUD fees if you buy a condo or a newer subdivision. Those fees may apply and cover amenities like pools or common-area maintenance.
Homeowners’ insurance costs in Central Texas vary, and rates depend on the home’s age, construction type, and proximity to flood zones.
When you calculate affordability, add the estimated tax bill, insurance, and any HOA fees to your mortgage payment. A simple spreadsheet can help you see the true monthly cost.
If your assessed value seems high, check the applicable appeal process and deadlines with the Williamson Central Appraisal District. An appeal may affect your final tax bill.
Understanding these ongoing costs helps you avoid surprises after you close.
What to Check Before You Make an Offer
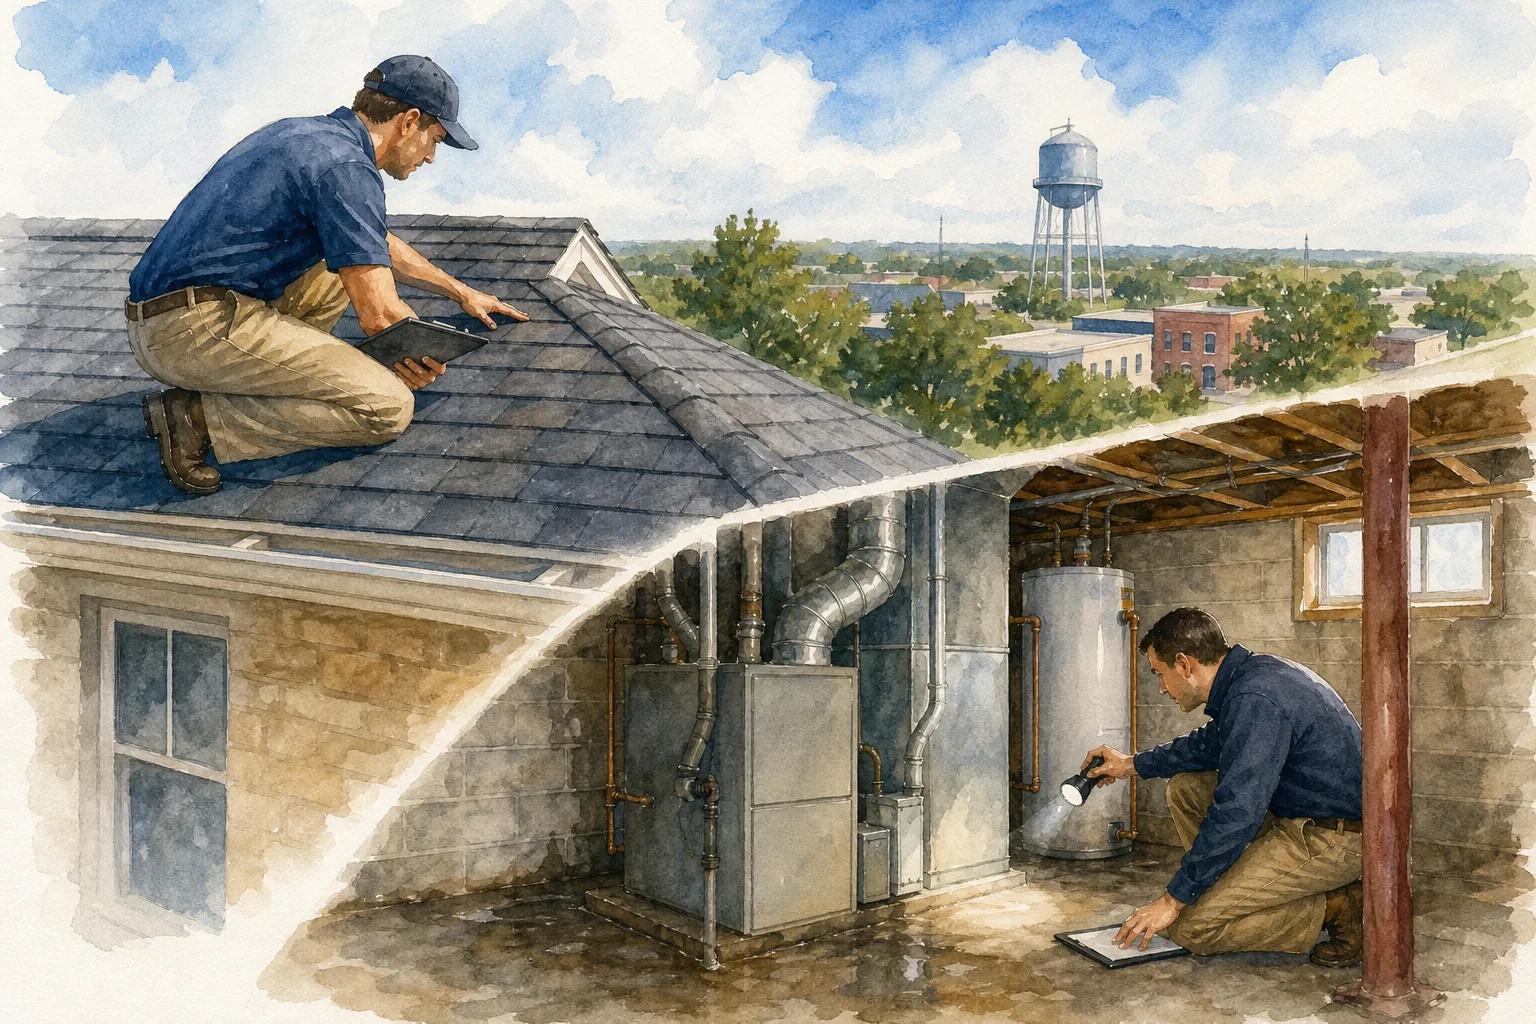
Before you write a check, run a thorough inspection checklist. A standard home inspection covers the roof, foundation, HVAC, electrical, and plumbing.
Older homes may have original wood windows, cast-iron drain lines, or pier-and-beam foundations. These items may need repair or replacement, so leave room in your budget for potential upgrades.
Check the seller’s disclosure for known issues. If the home is newer construction, ask whether a builder’s warranty is still in effect and when it expires.
Financing is another key step. Talk to a lender early so you know how much you can borrow. A pre-approval letter strengthens your offer and can speed up negotiations.
When you’re ready, consider a buyer’s representation agreement. Texas law lets you sign an agreement that obligates your agent to act in your best interest before you see any homes. Review the terms and ask questions so you understand the agreement before signing.
Finally, review the contract’s contingencies: inspection, financing, and appraisal. Each contingency gives you a way out if something unexpected shows up.
For a deeper look at the buying process, you can also read this related article.
How a Texas Home Purchase Moves From Offer to Closing
Once your offer is accepted, the Texas contract moves into a series of timed steps. The buyer typically deposits earnest money, often 1% of the purchase price, into an escrow account.
Next, the lender orders an appraisal. The appraiser checks that the home’s market value matches the loan amount. If the appraisal comes in low, you can renegotiate the price or ask the seller to cover the shortfall.
Simultaneously, the title company conducts a title search to ensure there are no liens or ownership disputes. In Texas, the title insurer also issues a title policy protecting both buyer and lender.
During this period, the buyer’s inspector delivers a detailed report. If major defects are found, you can request repairs, a price reduction, or a credit at closing.
After inspections and financing clear, the title company prepares the settlement statement. This document lists every cost, loan fees, prorated taxes, insurance, and the final purchase price.
On closing day, you sign the deed, the loan documents, and the settlement statement. The escrow agent then wires the funds, the deed is recorded with the county, and you receive the keys.
The whole timeline usually runs 30-45 days, but it can stretch if appraisal or financing issues arise. Staying in close contact with your lender, inspector, and agent keeps the process on track.
Frequently Asked Questions About Taylor, TX Homes for Sale
What is the average price of a home in Taylor?
The median list price is about $299 K, while the average price per square foot sits at $187 according to Realtor.com.
How long do homes stay on the market in Taylor?
On average, a home spends roughly 76 days on the market before going under contract.
Do I need a buyer’s agent in Texas?
You don’t have to, but a buyer’s agent works for you, not the seller, and can help you negotiate price, handle paperwork, and protect your interests.
What are the property tax rates in Taylor?
Property tax bills vary based on a home’s assessed value and applicable local taxing jurisdictions.
Can I get a mortgage pre-approval before looking at homes?
Yes. A pre-approval shows lenders you’re qualified for a loan amount and gives you stronger negotiating power when you make an offer.
Conclusion
If you’re ready to buy in Taylor, start by getting a pre-approval, use the market data here to set a realistic price range, and work with a local REALTOR who knows this growing community. Then schedule an inspection, review the contract contingencies, and move confidently toward closing. If you’d like to talk through a home you’re considering, I’m always happy to help.
Robbie English, REALTOR, Broker at Uncommon Realty