Robbie English, Broker and REALTOR

Helping Austin Home Buyers and Sellers Make Confident Real Estate Decisions

  • Buy
    • Search Homes For Sale
    • Featured Listings
    • Get Pre-Approved
    • Schedule a Buyer Consultation
    • Hire Me As Your Buyer’s Agent
    • Buyer Guides
      • Austin Home Buyer’s Guide
      • Austin Real Estate Guide
      • Austin Relocation Guide
      • Making an Offer
      • What Are Closing Costs?
      • Closing: Now What?
      • Financial Terms Glossary
    • Download The App
    • Neighborhood Guides
      • Neighborhood Guides
      • Highland Lakes Neighborhood Guides
    • Event Guides
      • Austin Metro Event Guides
      • Highland Lakes Event Guides
  • Sell
    • Sell With Me
    • Get Your Home’s Value
    • Schedule a Seller Consultation
    • Off-Market Representation
    • Market Snapshot
    • Seller’s Guide
      • Austin Home Sellers Guide
      • 11 Steps To Selling Your Home
      • Pricing Your Home
      • Marketing Your Home
      • Adding Value To Your Home
      • Showing Your Home
  • Rentals
    • Owner Portal
    • Featured Rentals
    • Rent
      • Resident Resources
      • Resident Portal
      • Tenant FAQ
      • Resident Benefit Package
      • Wear and Tear vs. Damage
  • Service Area
  • Blog
    • Find By Topic
    • Real Estate Resource Center
    • All Blog Posts
  • About
    • Testimonials
    • Robbie
    • Robbie’s Advanced Education
    • Uncommon Realty
    • Uncommon Diversity
    • Uncommon Path
  • Contact
Home » What Credit Score Do You Need to Buy a House?

What Credit Score Do You Need to Buy a House?

August 10, 2026 by Robbie English, REALTOR, Broker, ABR, AHWD, BBA, C2EX, CRB, E-PRO, GRI, MRP, PSA, RENE, RPR, SFR, SRS, TAHS, TBS, TLS

Thinking about buying a home but not sure if your credit score is high enough? The numbers matter, but there’s a clear range for each loan type. Below you’ll see the exact scores you need, why those scores matter, and what you can do if yours falls short.

Table of Contents

  • What Credit Score Do You Need to Buy a House?
  • Credit Score Requirements by Mortgage Loan Type
  • Why Your Credit Score Is Only One Part of Mortgage Approval
  • What to Do If Your Credit Score Is Too Low to Buy a House
  • FAQ
  • Conclusion

What Credit Score Do You Need to Buy a House?

At a bare minimum, government‑backed loans let you qualify with a score as low as 500. The FHA, for example, will consider borrowers at 500 if they can put down at least 10% of the purchase price; with a 3.5% down payment the floor rises to 580. The USDA requires at least 640, while the VA looks for 620, though many lenders prefer 720 for the best rates. Conventional loans usually start accepting applications around 620, but a score of 740 or higher gets you the most favorable interest rates.

These thresholds come from the same data set that shows the sweet spot for low rates sits roughly 200 points higher than the absolute minimums. That means you might qualify with a 580 score, but you’ll likely pay a higher rate than a borrower at 760.

For a deeper look at how credit scores affect mortgage eligibility, check out the detailed breakdown on What Type of Credit Score Is Needed to Apply for a Mortgage Loan?. It walks through the fair‑credit bands and how they line up with different loan products.

For more information about FHA loan options, visit the loan information page.

Credit Score Requirements by Mortgage Loan Type

Below is a quick reference that lines up the most common loan programs with their minimum scores, typical down‑payment percentages, and any special notes. This matrix helps you spot the options that match your credit profile.

Loan Type Minimum Credit Score Typical Down‑Payment Key Note
FHA 203(b) Loan 500 3.5% Allows borrowing up to 96.5% of the purchase price, including repair costs
FHA Manufactured/Home Mobile Loan — — Financing available for mobile homes and factory‑built housing, both land‑owned and park‑located
FHA 203(k) Loan — — Borrow full cost of fixer‑upper plus renovation costs up to FHA loan limit
HomeReady loan — (no hard floor listed) 3% Offers $2,500 credit toward down payment and closing costs
Conventional Loan — (recommended 740 for best rates) — Mentioned only as a comparison example; no specific credit score or down‑payment requirements are provided

Notice how loan programs can differ in credit requirements and down‑payment structure. Understanding that trade‑off can help you plan for moving costs, repairs, or an emergency fund.

For a side‑by‑side look at how conventional loans stack up against FHA, see Conventional vs FHA Loan. It breaks out the credit and payment differences in plain language.
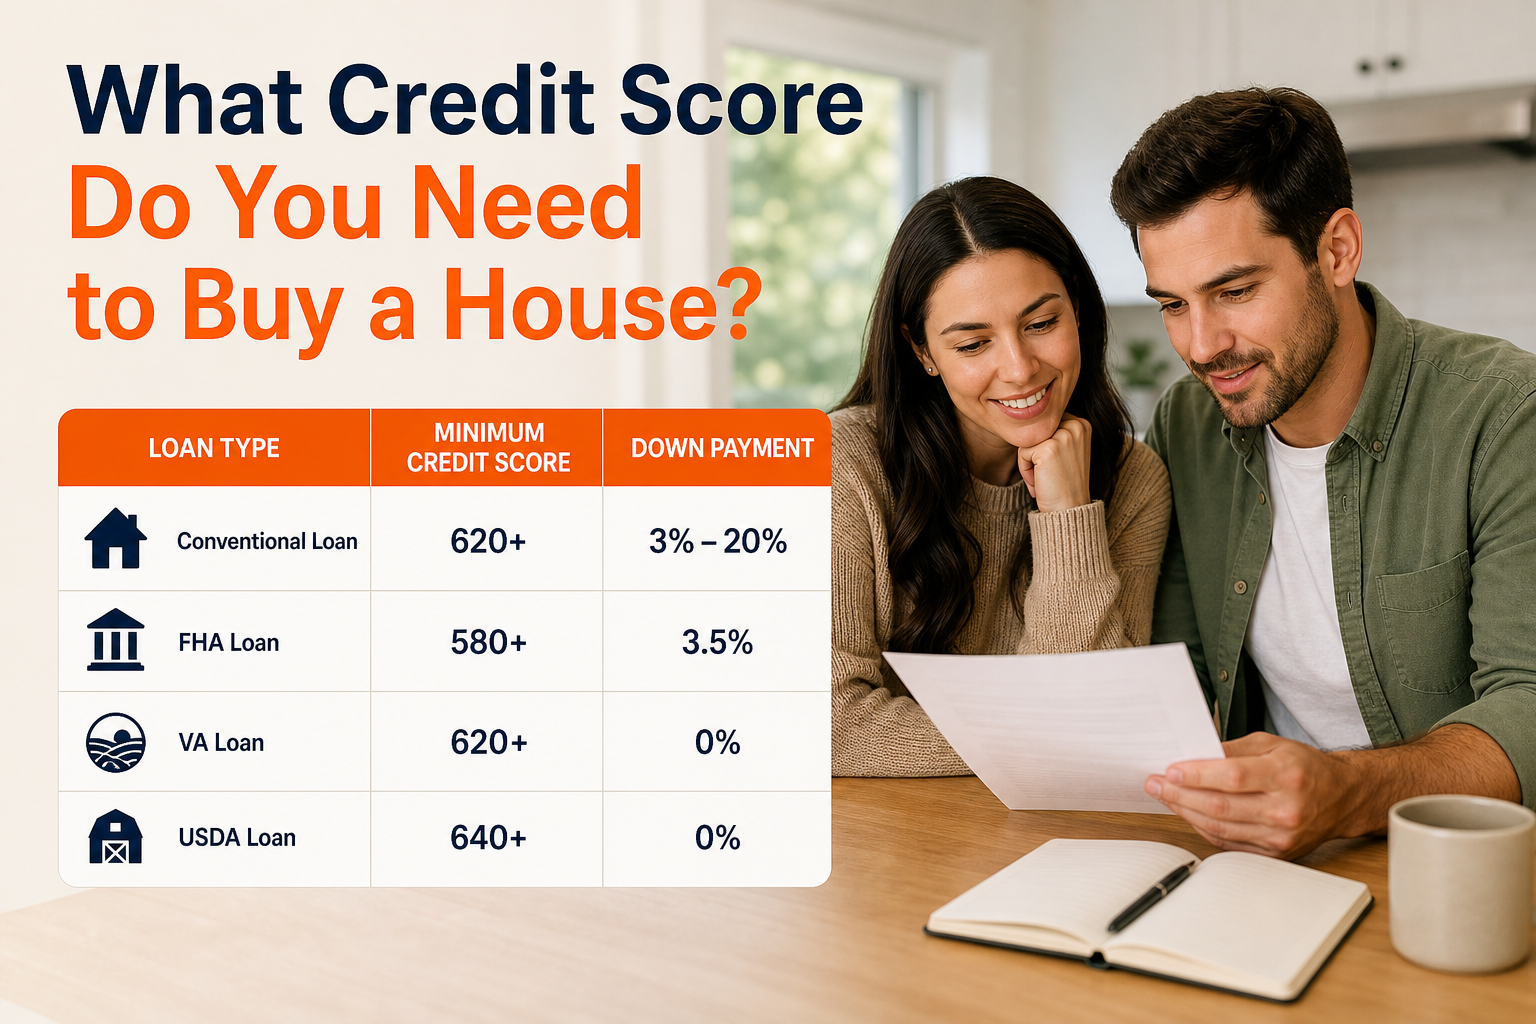
credit score requirements by mortgage loan type infographic

Why Your Credit Score Is Only One Part of Mortgage Approval

Lenders look at more than a single number. Your debt‑to‑income (DTI) ratio, employment stability, cash reserves, and the property’s appraised value all weigh heavily in the decision.

For example, a borrower with a 630 score but a low DTI (under 30%) and a sizable down payment might receive a better rate than someone with a 680 score but a high DTI and a thin cash cushion. The risk profile shifts when you bring more cash to the table; it shows you can handle the loan even if your credit isn’t perfect.

Lenders often ask for a larger down payment to offset a lower score. A bigger down payment reduces the loan‑to‑value (LTV) ratio, which makes the loan less risky for the bank.

Besides the score, lenders examine your payment history, total debt balances, and the length of your credit accounts. Those factors together paint a picture of how reliably you manage credit over time.
Pro Tip: Keep your credit utilization under 30% and avoid new hard inquiries for at least 30 days before you apply. Those simple moves can lift your score enough to cross a key lender threshold.

mortgage approval factors beyond credit score

What to Do If Your Credit Score Is Too Low to Buy a House

If your score lands below the minimum for the loan you want, you still have options. First, focus on the quick wins that can raise your score in a matter of months.

Pay down high‑interest credit‑card balances to bring utilization under 30%. Set up automatic payments so you never miss a due date; payment history is the biggest driver of your score. If you have old accounts you’re not using, keep them open, the length of credit history matters.

Another lever is to add positive payment data that isn’t automatically reported. Experian notes that services now let you report rent, utility, and streaming‑service payments to the bureaus, which can add several points.

Consider a credit-building product. These products let you demonstrate responsible usage without risking a hard pull on a regular credit card.

While you work on your score, you can also explore loan programs that tolerate lower numbers. The FHA’s 500‑score route, for instance, only requires a 3.5% down payment, which might be doable if you have savings ready. The VA and USDA also accept scores in the low‑600s for qualified borrowers.

Finally, get a free credit report from each of the three major bureaus and dispute any errors. A single mistaken late payment can knock off dozens of points.

Key Takeaway: Improving your credit score is a marathon, but targeted actions like lowering utilization and adding rent payments can produce noticeable gains in a few short months.

Need a step‑by‑step plan for picking the right lender? Check out How to Choose a Mortgage Lender in 2026. It walks you through questions to ask, documents to gather, and red flags to avoid.

FAQ

What is the lowest credit score I can have and still buy a house?

The absolute lowest score accepted by FHA loans is 500, with a typical down payment of 3.5%.

Do government-backed loans have a minimum credit score?

Some government-backed loans have minimum credit-score requirements, while others may depend on the lender and the overall application.

Can I get a government-backed loan with a credit score under the lender’s minimum?

Eligibility depends on the loan type, lender, and the rest of your application.

How does my credit score affect my mortgage interest rate?

Higher scores generally lead to lower interest rates, but the rate you receive depends on your overall application and lender.

If I have a low credit score, should I save for a larger down payment?

Yes. A larger down payment reduces the loan‑to‑value ratio, which can offset a low score and help you qualify for a better rate.

Where can I check my credit score for free?

All three major bureaus, Experian, Equifax, and TransUnion, provide a free annual credit report; many banks also offer free score views on their online dashboards.

Conclusion

If you’re ready to move forward, start by pinpointing which loan program matches your current score and down‑payment ability. Then grab a free credit report, fix any errors, and begin the small‑step credit‑boosting actions that can lift you into a better rate bracket. When you feel confident about your numbers, schedule a pre‑approval with a lender, it’s the fastest way to know exactly how much house you can afford.

For a next‑step guide on handling the pre‑approval process, head over to Get Pre‑Approved! – Robbie English, Broker and REALTOR.

Ready to put this into practice? Robbie English, REALTOR, Broker was built for exactly this.
Y'all Might Want To Check These Out Too...

The Perils of Being an Unrepresented Home Buyer: Why Competency MattersThe Perils of Being an Unrepresented Home Buyer: Why Competency Matters The Future of Real Estate Commissions: NAR Settlement AgreementThe Future of Real Estate Commissions: NAR Settlement Agreement Unlocking the Door to Second Home Investment: A Comprehensive AnalysisUnlocking the Door to Second Home Investment: A Comprehensive Analysis New Texas Homestead Exemption Regulations: What Homeowners Need to KnowNew Texas Homestead Exemption Regulations: What Homeowners Need to Know

Filed Under: blog

your dream home starts here
download closely
sell your home

Disclaimer: The content on this website is provided for general informational and educational purposes only. It is not legal, tax, accounting, financial, appraisal, or other professional advice. Reading these articles or contacting me through this website does not create a broker-client relationship. I am not an attorney, tax advisor, accountant, financial advisor, or licensed real estate appraiser. Only a licensed or certified real estate appraiser can provide a real estate appraisal. Only a licensed and certified appraiser can set a property’s value. Real estate laws, contracts, market conditions, and individual circumstances vary, so you should seek advice from the appropriate licensed professionals before making decisions.

start your home search

download closely

sell your home

Real Estate Resource Center by Robbie English

Pick a Topic:

Find Answers To Real Estate Questions Asked on Reddit

You may also like

The Perils of Being an Unrepresented Home Buyer: Why Competency MattersThe Perils of Being an Unrepresented Home Buyer: Why Competency Matters The Future of Real Estate Commissions: NAR Settlement AgreementThe Future of Real Estate Commissions: NAR Settlement Agreement Unlocking the Door to Second Home Investment: A Comprehensive AnalysisUnlocking the Door to Second Home Investment: A Comprehensive Analysis New Texas Homestead Exemption Regulations: What Homeowners Need to KnowNew Texas Homestead Exemption Regulations: What Homeowners Need to Know

Blog Article Topics

Absentee Owners • Austin Area Housing Market • Austin Real Estate • Austin Landlord Service • Build to Rent • Building A Home •  Cedar Park • Compensation • Distressed Homeowners • Downsizing • Financially Motivated • Find Your Place • First Time Home Buyers • For Sale By Owner • Greater Austin Housing Market • Green-Energy Efficiency • Homeowners Associations • Home Buying • Home Improvements • Home Pricing • Home Staging and Depersonalization • Home Values • Homeownership • Interest Rates • Investment and Vacation Rentals • Leander • Lifestyle • Living in Austin • Living in Cedar Park • Living in Central Texas • Living in San Antonio • Luxury Real Estate • Market Updates • Mortgage Financing • Moving to Austin • Moving to San Antonio • Moving to Texas • Multi-Generational Housing • My Advanced Education •  Negotiations • Off-Market Representation • Preparing for Closing • Probate and Estate Sales • Property Taxes • Real Estate • Refinancing Your Mortgage • Renting and Leasing •  Representation •  San Antonio Housing Market • San Antonio Real Estate • Selling Your Home • Selling Your Luxury Home • Short Term Rentals • Supply and Demand • Texas Property Management •  Trends

Search By Category

Blog Posts

Your Guide to the Kingsland House of Arts & Crafts Fall Show

Your Guide to the Kingsland House of Arts & Crafts Fall Show

The Average Monthly Rental Amount in Austin Has Dropped

The Average Monthly Rental Amount in Austin Has Dropped

How do I get my home organized enough to sell? | Ultimate Guide

How do I get my home organized enough to sell? | Ultimate Guide

Insider's Guide to Finding Your Ideal Real Estate Agent: Unveiling the Secrets

Why You Want and Need a Buyer’s Rep Agreement

Sellers Fear Non-Value Add Home Improvements

Sellers Fear Non-Value Add Home Improvements: What to Know Before You Spend

What to expect at home closing in Austin Texas

What to Expect at Home Closing

A couple at a kitchen table reviewing printed property photos, a bar chart report, and a laptop, with a calculator and notebook on the table

How to Buy a Second Home Step by Step

Robbie English, REALTOR, Broker

512-910-HOME (4663)

512-400-3082

830-953-5571

Uncommon Realty

Main Office:
5114 Balcones Woods Dr. Ste 307, Austin, TX 78759

Download My App
download my app

Common sense is a flower that doesn’t grow in everyone’s garden. That’s why we’re Uncommon!

I look forward to representing you! -Robbie

Robbie English Texas Real Estate Education Expert     Unlock MLS  Austin Board of REALTORS  Texas REALTORS  National Association of REALTORS  Highland Lakes Association of REALTORS

Find Homes For Sale in: Austin TX • Bee Cave TX • Burnet TX • Cedar Park TX • Cottonwood Shores, TX • Georgetown TX • Granite Shoals TX •  Highland Haven • Highland Lakes • Horseshoe Bay, TX • Hutto TX • Jonestown TX • Lago Vista TX • Lakeway TX • Leander TX • Marble Falls, TX • Manor TX • Pflugerville TX • Round Rock TX

My website uses state-of-the-art property search, including an interactive map search, to find homes for sale in the Central Texas Hill Country.

  • Buy
  • Sell
  • What’s My Home’s Value?
  • Search Properties
  • Service Area
  • Download App
  • Infographics
  • Real Estate Resource Center

© Copyright 2026 · All Rights Reserved · Robbie English, Broker, Property Manager, and REALTOR, National Instructor, Speaker

Privacy Policy • DCMA • Texas Real Estate Commission Information About Brokerage Services • Texas Real Estate Commission Consumer Protection Notice • Web Accessibility Help
All information deemed correct but not guaranteed.

Accessibility Adjustments

Powered by OneTap

How long do you want to hide the toolbar?
Hide Toolbar Duration
Select your accessibility profile
Vision Impaired Mode
Enhances website's visuals
Seizure Safe Profile
Clear flashes & reduces color
ADHD Friendly Mode
Focused browsing, distraction-free
Blindness Mode
Reduces distractions, improves focus
Epilepsy Safe Mode
Dims colors and stops blinking
Content Modules
Font Size

Default

Line Height

Default

Color Modules
Orientation Modules