Buying your first Austin-area home may be possible without taking on a payment that strains your budget. The key is to look beyond the list price and compare each neighborhood by property taxes, insurance, HOA dues, commute costs, loan terms, and any MUD or PID charges. As I would explain to a buyer sitting with me in Austin, I’ll show you how to narrow the search, where available pricing data can help, and which questions still require a closer look in Central Texas.
TL;DR
- Lower-cost options often sit east, south, or north of Austin rather than near the urban core.
- Available price data is uneven, so treat broad labels such as “under $500,000” as a starting point.
- Your full payment includes principal, interest, property taxes, insurance, HOA dues, and possible MUD or PID charges.
- New construction may include incentives, but the tax bill and HOA budget still need review.
- Visit areas at your actual commute time before you make an offer.
Start With an Austin-Area Affordability Map
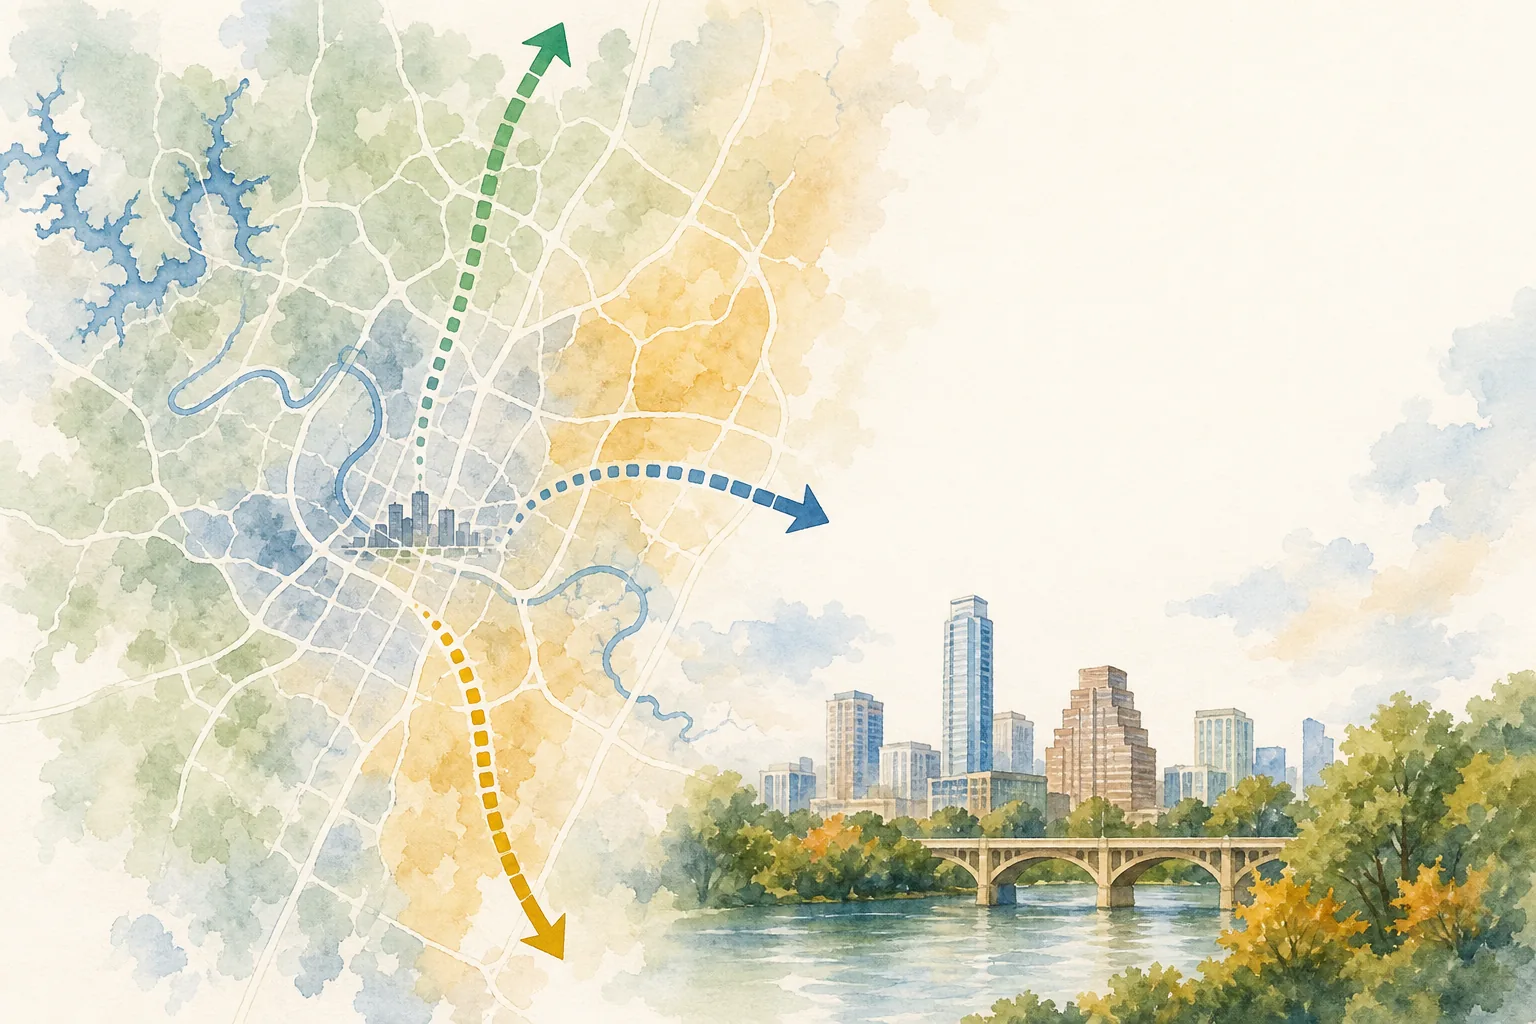
When I help a first-time buyer search for affordable Austin neighborhoods, I start with a map rather than a favorite area. Lower entry points often appear in communities such as Del Valle, Manor, Hutto, and Pflugerville. Each can change the purchase math, but each also brings a different commute, tax structure, housing stock, and level of new development.
The available figures are useful, but they are not a complete market report. A price range cannot tell you what a typical home costs when the terms and sources are inconsistent.
| Area | Available price signal | What to check before deciding |
|---|---|---|
| Del Valle | $350K-400K | Commute, new development, tax districts |
| Pflugerville | Under $400K | Tax bill, HOA dues, route to work |
| Hutto | — | Builder supply, commute, resale competition |
| Manor | $375K-425K | Retail access, construction activity, taxes |
| Kyle | — | I-35 traffic, insurance, home condition |
| Taylor | — | Employment growth assumptions and reserves |
| Maple Run | Under $500,000 | Exact recent sales, property condition |
| Buckingham | Under $500,000 | Exact recent sales, HOA and tax records |
I would also keep Buda, Georgetown, Elgin, and Lockhart on the wider map when the commute works for you. Buda and Kyle sit south along I-35. Hutto and Georgetown extend the search north. Manor and Elgin sit east. Lockhart may reduce the purchase price further, but distance becomes a larger part of the budget, especially if you travel into Austin regularly.
For context, broader Austin-area and city benchmarks can provide perspective, but they are broad comparisons, not a promise about any particular subdivision or home. Use current Austin homes under $500,000 to see how property type, condition, and location change what that budget buys in the Austin area.
One thing I have learned over more than 40 years in real estate is that a cheaper map point does not always produce a cheaper life. A longer drive can add tolls, fuel, vehicle wear, and lost time. A newer subdivision can bring lower repair risk but higher taxes or HOA dues. Before choosing an Austin-area neighborhood, keep both sides of that ledger in view and verify the current numbers for the specific property.
Compare the Monthly Cost, Not Just the Purchase Price
Affordable Austin neighborhoods for first-time buyers only work when the full monthly payment fits your budget. A home priced at $350,000 can cost more each month than a higher-priced home if the first property has higher taxes, insurance, HOA dues, or special district charges.
Ask your lender to show the payment in separate parts:
- Principal and interest on the loan.
- Property taxes based on the actual parcel.
- Homeowners insurance and any required coverage.
- HOA dues, including transfer or resale fees.
- MUD, PID, or other district charges shown in the tax records.
- A monthly repair reserve for the age and condition of the home.
Texas property taxes depend on the taxing units tied to the property. The tax amount shown in a listing may also change after a sale or after exemptions are applied. I would review the county appraisal record, current tax statements, and projected lender figures before treating any payment estimate as final. My guide to Austin property tax rates by area explains why two nearby homes can carry different bills.
HOA dues deserve the same care. Read the budget, rules, pending assessments, and maintenance responsibilities. A low fee may leave more exterior work with you. A higher fee may cover shared features or yard care, but it can still rise later. Ask what the fee covers today, not what a sales sheet suggests may come later.
Then add the cost of getting to work. A 25-minute drive outside rush hour may become much longer when traffic builds. Test the route at the time you would actually leave. If toll roads make the trip tolerable, include that charge in your monthly budget.
I also want you to keep cash after closing. A low down payment can preserve savings, but it doesn’t remove the need for reserves. Repairs arrive on their own schedule. So does a higher insurance renewal.
Use Financing, Assistance, and New Construction Carefully
Financing can change which Austin-area homes fit your budget, but assistance is not free money with no conditions. State and local programs may have income, purchase-price, credit, occupancy, or repayment rules.
Ask a qualified lender to compare the full cost of each option. Review the interest rate, lender fees, mortgage insurance, cash needed at closing, and the payment after any temporary incentive ends. A lower upfront cost may be helpful, but a higher long-term rate can change the result.
Down-payment assistance may work well for one buyer and poorly for another. Some programs use a deferred second lien. Others may require repayment when you sell, refinance, or stop using the home as your primary residence. Get the terms in writing. Don’t rely on a headline that only mentions the grant amount.
New construction deserves its own worksheet. Builders may provide closing-cost help, rate reductions, upgrades, or other incentives. Compare the final price after incentives with nearby resale homes. Also ask whether the incentive requires the builder’s lender or title company. You are free to choose your own providers, even when a builder has a preferred team.
A new home can reduce near-term repair work, but it does not remove every risk. Review the lot, drainage, construction timeline, warranty terms, HOA budget, and projected taxes. If the subdivision sits in a MUD or PID, confirm the current charge and how it affects the payment. A model home can look complete while roads, retail, or planned amenities remain unfinished.
Some buyers also consider a duplex, a home with a separate unit, or a property with a room that could support rental income. Treat that income as a possible offset, not guaranteed approval math. Check zoning, lending rules, insurance, parking, leases, and local restrictions before counting on it.
For a step-by-step review of loan paperwork and cash needs, my page on the mortgage preapproval process can help you prepare better questions. I can help you compare homes, but your lender must confirm what you qualify for.
Check Commutes, Zoning, Schools, and Future Resale Factors
Price is only one filter when you compare affordable Austin neighborhoods for first-time buyers. I would put the daily route beside the home search from the first day. Kyle may work for a buyer headed to south Austin. Manor may make more sense for an east-side commute. Hutto may fit someone working north or east. The same price can feel very different after a month of driving.
School boundaries also require parcel-level research. Attendance zones can change at a street or subdivision line, and online summaries may be out of date. Verify the assigned schools with the district and ask how the boundary is confirmed for the exact address. Academic ratings can be one factor, but they should not replace a review of the home, payment, and commute.
Zoning matters when you are considering an accessory unit, duplex arrangement, home business, or future addition. Check the city or county rules before you assume a plan is allowed. HOA restrictions can add another layer. A property that looks perfect for a second unit may not support one under current rules.
For resale, look at the features buyers can verify later: access to major roads, realistic upkeep, floor plan, parking, drainage, and the condition of nearby development. Don’t buy on a promise that a future project will raise values. Infrastructure schedules can change. New supply can also give buyers more choices and limit your pricing power.
Market data has limits here. The material available for these areas does not provide consistent price-to-income ratios, average days on market, or school ratings. I would ask for current comparable sales, listing-time data, tax records, and insurance estimates before making a decision.
Before you tour, write down your decision rules. For example, you might accept a longer commute for a lower payment, but not a high HOA. Or you might prefer an older home near Austin if the inspection is clean and the tax bill is manageable. Clear rules keep a pretty kitchen from taking over the whole decision.
Texas buyers should also understand the agreement they sign with their agent and what it covers. A plain-language review of a buyer representation agreement in Texas can help you prepare questions about services, term, and compensation before touring homes. Ask for those details in writing, and make sure you understand how the agreement applies to the properties and services you are considering.
Common First-Time Buyer Mistakes to Avoid
The most common mistake is setting a price ceiling without setting a payment ceiling. Start with the payment you can carry after savings, transportation, utilities, and repairs. Then let the lender show you the matching price range.
- Don’t use a builder’s incentive to hide a payment that only works for a short period.
- Don’t assume the listing tax estimate is your final bill.
- Don’t skip an inspection because a home is new.
- Don’t assume a future amenity is open or fully funded.
- Don’t compare a city home with a suburban home without adding commute costs.
- Don’t make an offer before checking insurance availability and deductibles.
Robbie English, REALTOR, Broker is my business, and I work with buyers across Austin and nearby Texas communities. My role is to help you ask better questions and compare the trade-offs. You are free to choose any lender, inspector, title company, or other provider you want. I can share experienced professionals I have intentionally curated, but using them is never required.
Frequently Asked Questions
What are the most affordable Austin neighborhoods for first-time buyers?
Nearby areas such as Buda, Elgin, Georgetown, and Lockhart may also belong on your map.
How much should I budget for a first home near Austin?
You should budget from the full monthly payment rather than the purchase price alone. Include principal, interest, taxes, insurance, HOA dues, district charges, utilities, transportation, and repairs. A lender can estimate loan costs, while your agent can help you compare the property-specific expenses that listings often leave out.
Is new construction cheaper for first-time buyers?
New construction can reduce near-term repair needs, but it is not always cheaper overall. Builder incentives may lower closing costs or the initial interest rate. You still need to review taxes, HOA dues, district charges, lot costs, warranty terms, and the payment after the incentive ends. Compare the final numbers with resale homes nearby.
Should I buy farther from Austin to get a lower price?
Buying farther out can lower the purchase price, but the trade-off may be time, tolls, fuel, and vehicle wear. Test your actual commute during the hours you travel. Areas such as Kyle, Manor, Hutto, and Georgetown can have different trade-offs, so the right choice depends on your job location and payment budget.
What should I verify before making an offer?
Verify the property’s tax history, insurance quote, HOA documents, district charges, assigned schools, inspection needs, and current comparable sales. Also confirm any zoning or rental restrictions that affect your plans. This checklist matters because affordable Austin neighborhoods for first-time buyers can look similar online while carrying very different monthly costs.
Conclusion
I recommend choosing two or three areas that fit your payment and commute, then comparing actual homes rather than relying on broad neighborhood labels. Start with a lender-approved budget, request property-specific tax and insurance figures, and visit each area at your normal travel time. If you want a second set of eyes on the trade-offs, Robbie English, REALTOR, Broker can help you build that search without making the decision for you.