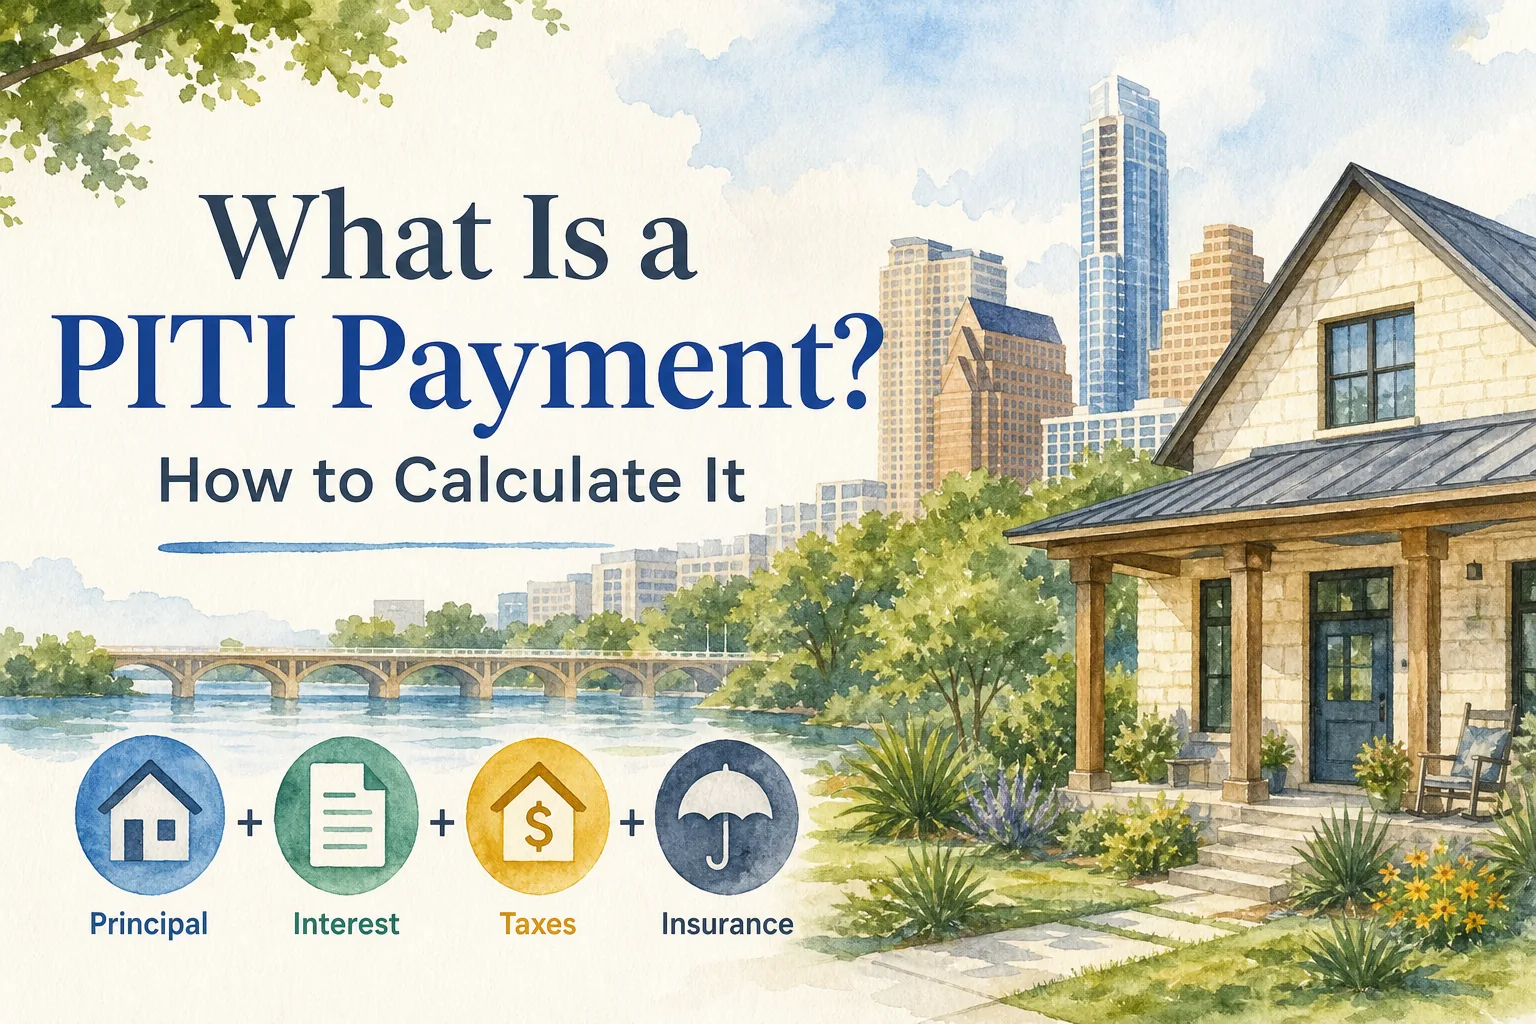
A mortgage payment is more than the amount you borrow. When someone asks me, “What is a PITI payment?” I explain that it combines principal, interest, property taxes, and homeowners insurance. Add those parts one by one to get a clearer estimate of your monthly housing cost.
Too Long; Didn’t Read
- PITI stands for principal, interest, property taxes, and homeowners insurance.
- Many lenders collect the tax and insurance share each month through escrow.
- PMI and HOA dues can sit on top of PITI, so check whether they apply.
- Property taxes and insurance vary by address, so estimate them for each home.
- Even with a fixed rate, your total payment can change when taxes or insurance change.
Step 1: Identify What Your PITI Payment Includes
PITI is a way to describe four parts of a home loan payment. Principal pays down the amount you borrowed. Interest is the cost of borrowing. Property taxes go to local taxing authorities, while homeowners insurance helps cover losses named in your policy.
Many lenders collect taxes and insurance each month in an escrow account, then pay those bills when due. Some borrowers pay them directly instead. Either way, include the monthly share in your budget. A lender may also count private mortgage insurance, or PMI, when it applies. PMI protects the lender, not you, if you stop paying the loan.
Think of the full PITI figure as the monthly cost of the loan and key home-related bills, not the whole cost of owning a home.
In Austin, the tax estimate can vary by property and taxing units. A home in Travis County may have a different total tax rate than one in Williamson or Hays County. Before comparing homes, check the taxes tied to each address. I explain the account mechanics in my guide to how a mortgage escrow account works.
One more detail: some lenders use PITIA, adding association dues to the calculation. HOA dues may be paid separately, but they can still affect what you can afford.
Step 2: Estimate Principal and Interest
Start with the loan amount, interest rate, and loan term. These three inputs determine the principal-and-interest portion for a fixed-rate loan. Your down payment affects the loan amount, while the rate and term come from the loan terms you’re considering.
The standard monthly payment formula is M = P × [r(1+r)^n] ÷ [(1+r)^n − 1]. Here, P is the amount borrowed, r is the monthly interest rate, and n is the total number of monthly payments. To find r, divide the annual rate by 12. For a 30-year loan, n is 360.
You don’t have to solve the equation by hand. Enter the loan amount, rate, and term into a mortgage calculator, then check that the result shows principal and interest only. The estimated payment depends on those inputs, so use the terms you’re considering to calculate your own estimate.
That figure is only the loan portion. It leaves out taxes, homeowners insurance, and PMI. An adjustable-rate payment may be recalculated when the rate changes. A fixed rate keeps the interest rate steady, but it doesn’t freeze the rest of your PITI.
When you test scenarios, change one input at a time. Compare a larger down payment, a different loan term, or a rate your lender has quoted. That makes it easier to see which change moves the monthly payment. For a broader budget check, I’ve laid out how to think about the home price you can afford.
By now, you should have a monthly principal-and-interest estimate. Keep it separate from the other costs until you have property-specific tax and insurance figures.
Step 3: Estimate Property Taxes and Homeowners Insurance
For a first estimate, take the annual property tax amount and divide by 12. Do the same with the annual homeowners insurance premium. Add those monthly shares to principal and interest. If you’re still comparing homes, use a current tax estimate for each address rather than carrying one number from house to house.
In the Austin area, the tax bill can reflect more than one taxing unit. County, city, school district, and special district taxes may all affect the total. My guide to Austin property tax rates by area explains why the address matters when you build a monthly estimate.
Insurance needs an address-specific quote, too. Coverage, the home’s rebuild cost, roof details, and the insurer’s terms can all affect the premium. Ask for an estimate early enough to include it in your budget and share it with your lender. A general statewide or national figure can help with rough planning, but it isn’t a substitute for a quote on the home you’re considering.
For a simple illustration, use a monthly property-tax estimate of $500 and a monthly homeowners insurance estimate of $500. Add those amounts to principal and interest, then account for PMI or other costs if they apply. These are illustrative inputs, not Austin-area averages or a quote.
In Austin, I’d also check whether the estimate reflects the property’s current tax details and the insurance terms for that specific home. My guide to the way Texas property taxes affect a home purchase can help you frame the right questions as you review the numbers.
Step 4: Add the Components and Check for Costs Outside PITI
Add the monthly principal-and-interest amount to the monthly tax and insurance shares. Then add PMI if your loan requires it. Your result is a useful PITI estimate, but check the loan documents to see which costs the lender includes in the payment and which you’ll pay separately.
PMI can apply to some conventional loans when the down payment is below 20%. The exact rules and cost depend on the loan and borrower. A lower down payment may preserve more cash for other needs, but it can also add a monthly insurance charge.
HOA dues are another cost to check. They’re often paid to the association rather than through the lender, yet a lender may include them when assessing your debts. A condo or planned community can also have other property-related charges. Confirm the amount and payment schedule for the specific home instead of assuming those costs are part of escrow.
PITI doesn’t cover every bill that comes with owning a home. Utilities, repairs, routine upkeep, and possible special assessments need their own room in your household budget. The monthly mortgage payment may look manageable while the full cost feels tight once those bills arrive.
For an affordability check, divide monthly PITI by gross monthly income to get a housing-cost ratio. Then include your other monthly debt payments to estimate total debt-to-income ratio. Some lenders use 28% as a guide for housing costs, but that isn’t a universal approval rule. Loan programs and borrower details differ. Ask your lender how it counts association dues and other debts in that review.
Step 5: Verify the Estimate and Plan for Changes
A calculator gives you a starting point. A lender’s Loan Estimate gives you loan-specific figures to review, and the Closing Disclosure confirms key costs before closing. Check that the loan amount, rate, term, tax estimate, insurance premium, and PMI match the assumptions you used.
Ask the lender which costs are included in the monthly payment and whether taxes and insurance will go into escrow. If there is an escrow account, the lender collects funds during the year and pays the bills when they come due.
Even with a fixed-rate mortgage, your total monthly payment can change. Property taxes may change after an assessment or rate change. Insurance premiums can change at renewal. When the lender reviews escrow and finds that the account needs more funds, the monthly collection may rise. That’s separate from a change to the loan’s fixed interest rate.
To keep the estimate current, review tax and insurance figures when you get new information about the home. After closing, read your annual escrow statement and compare the projected bills with the amounts collected. If the payment changes, identify which part changed before adjusting your budget.
For buyers in Greater Austin, I’d treat the address as the starting point for the tax estimate and the insurance quote. As a broker, I help buyers work through the property, contract, financing, and timing decisions together. I don’t set loan terms or insurance prices, so confirm those figures with the lender and insurer you choose.
Frequently Asked Questions About PITI Payments
What does PITI stand for in a mortgage?
PITI stands for principal, interest, taxes, and insurance. Principal repays the loan balance, while interest is the cost of borrowing. Taxes refer to property taxes, and insurance usually means homeowners insurance. PMI may be added for some loans, though it isn’t one of the four letters. Your lender can confirm which parts appear in your monthly bill.
Does PITI include HOA fees?
Usually, HOA dues aren’t part of the four PITI components, and owners may pay them directly to the association. Still, a lender may count the dues when reviewing your monthly debt and housing costs. Add them to your own budget even if they don’t appear in the mortgage payment shown by the lender.
Can my PITI payment change with a fixed-rate mortgage?
Yes. A fixed-rate loan keeps its interest rate steady, but taxes and insurance can change. If those bills rise, an escrow review may lead to a higher monthly collection. The principal-and-interest portion generally stays level on a standard fixed-rate loan, but the total amount you pay each month may not.
How do I calculate a monthly PITI payment?
First, calculate monthly principal and interest using the loan amount, interest rate, and term. Divide the annual property tax by 12, then divide the annual homeowners insurance premium by 12. Add those amounts and any required PMI. Include HOA dues and other home costs separately if they aren’t part of the lender’s payment.
Do lenders use PITI to decide how much I can borrow?
Yes. Lenders consider the expected housing payment when they review affordability and debt-to-income ratios. They may include other monthly debts in that review, too. A preapproval can help you understand the lender’s estimate, but I’d compare it with your full budget, including bills that don’t appear in PITI.
Conclusion
Build your estimate with the loan terms, tax amount, and insurance quote for the home you’re considering. Then add PMI if it applies and budget separately for HOA dues and upkeep. If you’re looking in Greater Austin, I can help you think through the property and purchase decisions; confirm loan and insurance figures with your chosen professionals. Robbie English, REALTOR, Broker at Uncommon Realty.